
SHOP TYPES
What Type of Auto Service Property Are You Financing?
Many auto repair owners use SBA loans. Owner-operators who stop leasing and buy their own shop build equity.
General Repair / Independent
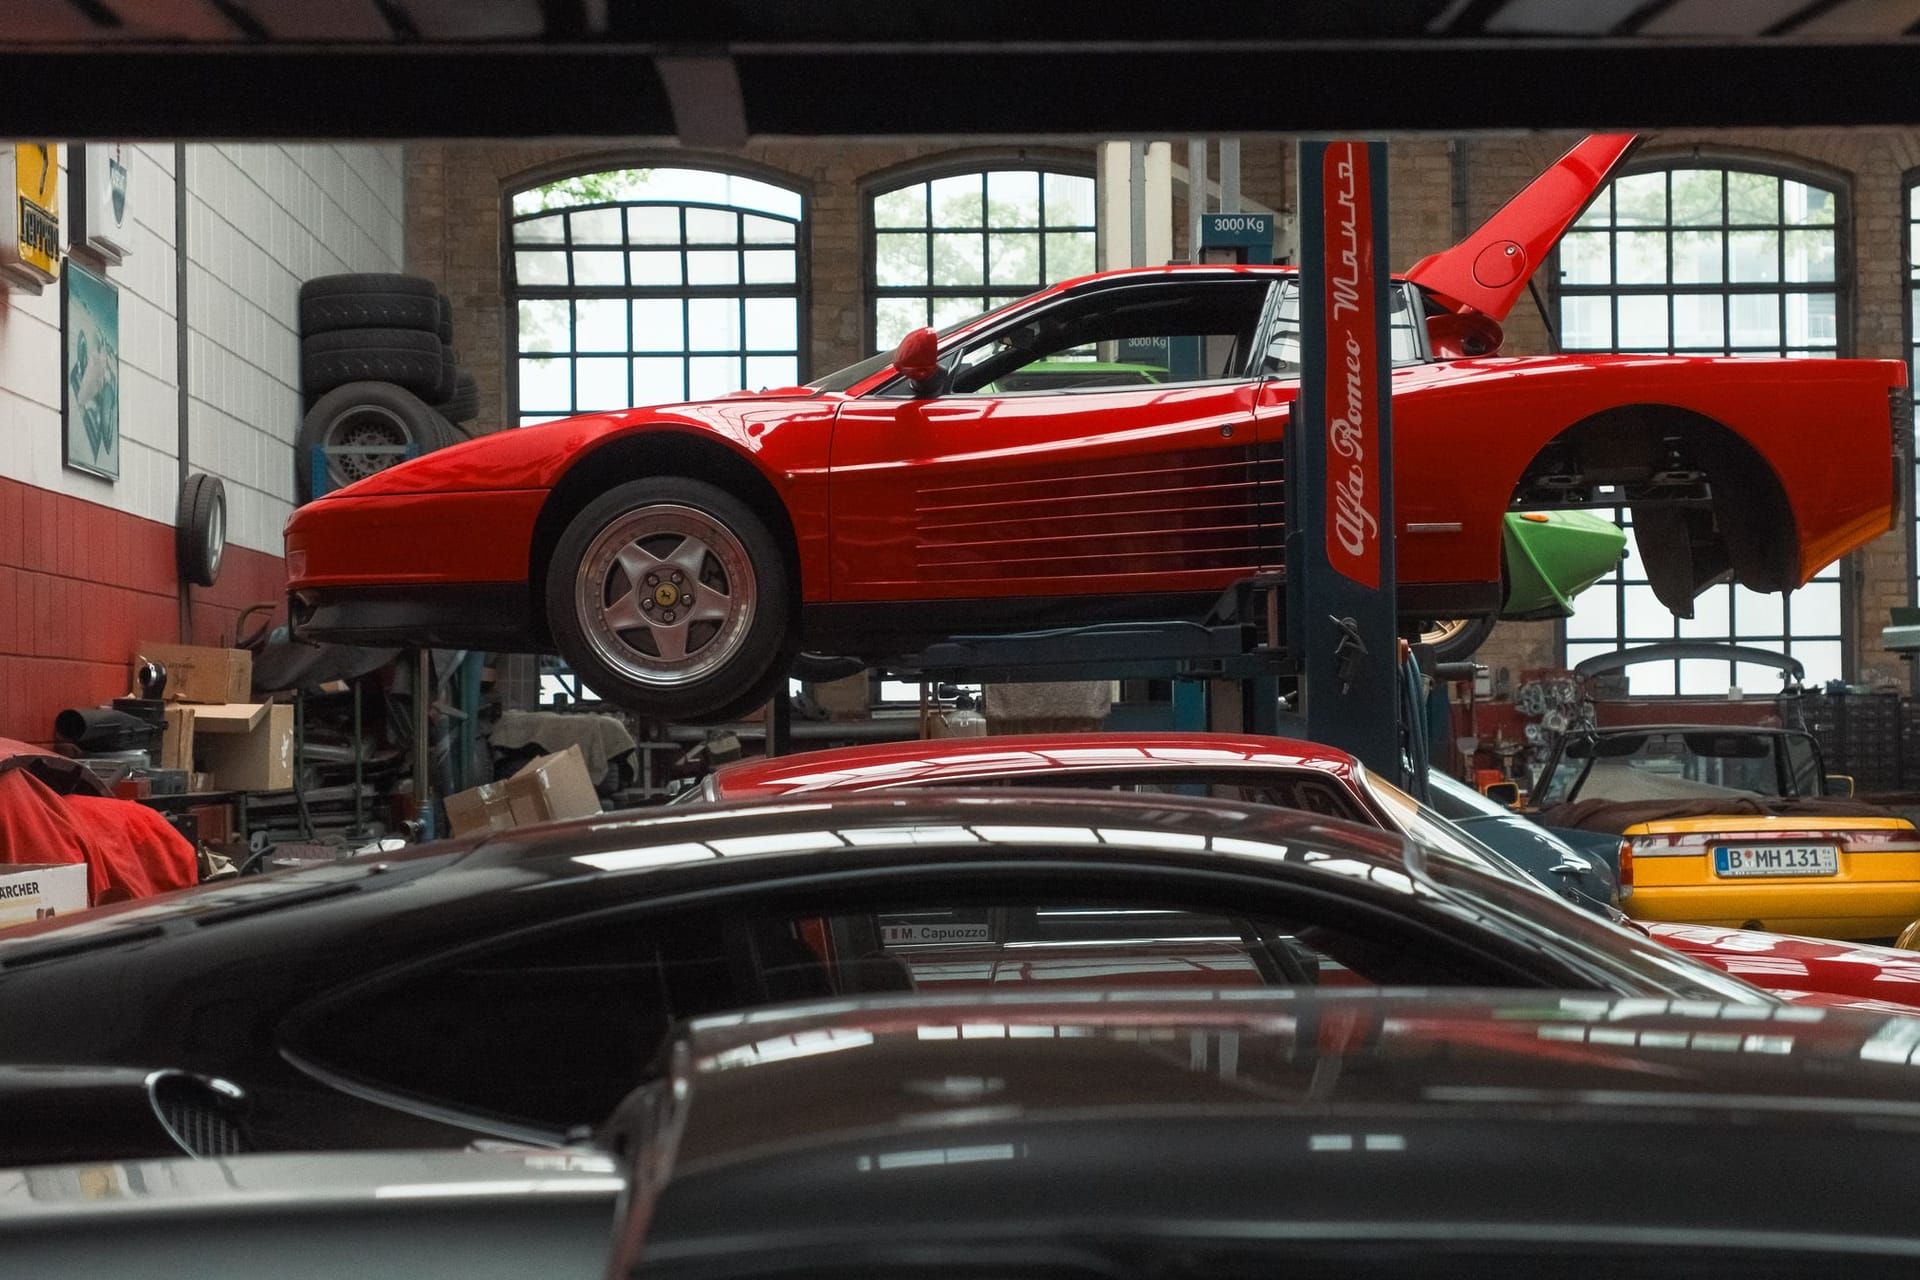
Multi-bay, full-service garage2–10 bay shops handling oil changes, brakes, engines, diagnostics. Typically owner-operated. SBA 504 is a common path to ownership (10% down, 15% if SBA treats it as special-purpose).
Franchise Service Center
Jiffy Lube, Midas, Meineke, AAMCOFranchise-backed service operations with brand recognition and proven systems. Franchise backing improves lending terms. Drive-thru oil change facilities and specialty shops (transmission, exhaust) fall here.
Specialty / Body Shop
Collision, paint, restorationCollision repair, paint booths, and specialty restoration shops. Higher buildout cost for spray booths, ventilation, and environmental compliance. Insurance relationships (DRP programs) provide steady revenue streams.
FINANCING OPTIONS
Loan Options for Auto Repair Properties
SBA is a common path for auto repair owners. Most shops are owner-occupied, making SBA 504 and 7(a) ideal.
SBA 504
Best for buying your shop, 10–15% downCovers real estate + lifts, alignment machines, and diagnostic equipment. Bank first lien plus a fixed-rate SBA (CDC) second.
SBA 7(a)
Flexible — RE + equipment + working capitalCombine property purchase, shop equipment, parts inventory, and opening working capital in one loan. Variable rate but maximum flexibility.
Conventional Bank
Established shops, fastest closeFewer forms, faster close. Best for established shops with 3+ years and strong financials.
Equipment Financing
Lifts, alignment, diagnostic toolsFor equipment purchases separate from real estate. 2-post and 4-post lifts, alignment machines, scan tools, AC machines.
Typical ranges, updated September 2026. Your terms depend on the property, the borrower and the lender.
KEY METRICS
What Lenders Evaluate for Auto Repair Loans
WORKED EXAMPLE
Example: Building and Lifts — One Loan or Two?
Example: a shop owner buys a $1,350,000 six-bay building with 10% down through SBA 504 and needs $150,000 of new lifts, an alignment rack and diagnostic tools. Assumptions for illustration only: a 6.5% CDC rate fixed for 25 years and a 7.0% bank rate amortized over 25 years; equipment financing at an example 8.5% over 5 years. Computed with our SBA 504 calculator and the same payment formula.
| Amount | |
|---|---|
| Down payment on the building (10%) | $135,000 |
| SBA 504: CDC $540,000 + bank $675,000 | $3,646 + $4,771 = $8,417/mo |
| Equipment loan: $150,000, 5 years | $3,077/mo for 60 months |
| Total for the first five years | $11,494 a month |
Separate equipment financing keeps the equipment off the 25-year real estate schedule and pays it off within its working life; rolling long-life equipment into the 504 project instead lowers the monthly cost but stretches it. Either way, expect a Phase I environmental report — shops handle oil, solvents and coolant, and a former gas station on the site means tank history to clear.
Typical ranges, updated September 2026. Your terms depend on the property, the borrower and the lender.
THE PROCESS
How Auto Repair Financing Works
Define Your Project
Buying an existing shop, building out a new space, or purchasing equipment? Share property details, bay count, and equipment needs.
Submit to BestLoanUSA
Single application with shop financials, personal credit, and property details. No hard credit pull.
Advisor Review
Dedicated advisor evaluates your shop performance, equipment needs, and environmental considerations to recommend SBA, conventional, or equipment financing.
Lender Matching
We submit to lenders experienced in auto service properties. You receive competing offers.
Underwriting & Appraisal
Special-purpose appraisal + Phase I Environmental. Provide 2 years tax returns, P&L, equipment list, and purchase contract.
Close & Operate
SBA: 30–90 days. Conventional: 30–45 days. Equipment: 7–14 days. You own your shop and stop paying rent.
Free tools
Run the numbers
The same metrics a lender checks — free, instant, no signup. Each result links straight into an application.
- SBA 504 Loan Calculator Estimate your SBA 504 loan structure — see the three-part split (borrower, CDC, bank), monthly payments for each portion, and total project financing.
- SBA 7(a) Payment Calculator Estimate monthly payments on an SBA 7(a) loan with Prime + spread variable rate. See how rate changes affect your payment and plan for different scenarios.
FAQ
Frequently Asked Questions
Should I buy or lease my auto repair shop?
If you plan to operate 5+ years in the same location, buying builds equity and locks in costs. With SBA 504 at 10–15% down, monthly ownership cost can be comparable to rent. Auto repair shops have specialized infrastructure (lifts, pits, ventilation) that’s expensive to rebuild, so owning gives you control of your most critical asset.
What does it cost each month to buy an auto repair shop building?
In our example, a $1,350,000 building bought with SBA 504 and 10% down ($135,000) costs about $8,417 a month at an example 6.5% CDC rate and 7.0% bank rate, plus $3,077 a month for five years if you finance $150,000 of lifts and diagnostic equipment separately. If SBA treats the building as special-purpose, the down payment is 15%.
Can I include lift and equipment costs in my loan?
Yes. SBA 504 and 7(a) allow you to roll equipment into the total project. Two-post and four-post lifts, alignment machines, AC recovery units, scan tools, and tire equipment can all be included. One loan covers everything.
Do environmental issues affect auto repair lending?
Yes. Auto shops handle hazardous materials (oil, coolant, solvents). All lenders require a Phase I Environmental Site Assessment. If the property has underground storage tanks (USTs) from a former gas station, Phase II testing may be needed. Clean environmental reports are required before closing.
What revenue do I need to qualify?
SBA sets no minimum revenue; lenders usually want 2+ years of operating history. Your personal and business DSCR should be 1.20x+ after the new payment. Franchise-backed shops (Jiffy Lube, Midas) may get more favorable treatment due to brand credibility.
Can I buy an existing shop with its business?
Yes. SBA 7(a) can combine the business acquisition (goodwill, customer base, equipment) with the real estate purchase in one loan up to $5M. This is common when a retiring shop owner sells the entire operation including the property.
What about body shops and collision repair?
Body shops have additional requirements: spray booth ventilation, environmental compliance for paint, and hazardous waste handling. Buildout costs are higher than for general repair. Insurance DRP relationships can provide steadier revenue that strengthens loan applications.
Related on BestLoanUSA
Financing options
All loans →- Auto Dealership An auto dealership real estate loan finances the land and buildings a dealer operates from — showroom, service bays and lot — to buy, expand, refinance or complete an OEM image upgrade. Owner-operators often use SBA 504 or a bank loan, at about 6.25–8.75%. AutomotiveSBA 504
- Car Wash A car wash loan finances the purchase, ground-up construction or refinance of a car wash property — express tunnel, self-serve or full-service. Owner-operators often combine SBA or bank financing for the real estate with equipment financing for the wash system. AutomotiveSBA 504
- C-Store & Gas A gas station or convenience store loan finances the property and, for an owner-operator, often the business with it. Owner-operators commonly use SBA loans with 15% down, since lenders treat these as special-purpose properties; investors buying a net-leased c-store use DSCR or bank loans at about 6.75–8.75%. AutomotiveSBA 504
- Owner-Occupied An owner-occupied commercial real estate loan finances a building your own business uses — for SBA loans, at least 51% of an existing building or 60% of a new one. SBA 504 and 7(a) allow as little as 10% down; conventional bank loans usually need more, at rates around 6.25–8%. AutomotiveSBA 504
Guides & articles
All articles →- SBA 504 Loans for Commercial Real Estate: 10% Down How the SBA 504 loan lets a business buy its own commercial property with as little as 10% down — the structure, who qualifies, costs and the process. AutomotiveSBA 504
- SBA 7(a) vs. SBA 504: Which SBA Loan Do You Actually Need? Both are SBA loans — but they work completely differently and are right for different situations. Here's the side-by-side that tells you which one fits your need. SBA 504SBA loans
- SBA 504 vs Conventional Commercial Mortgage: Cost and Fit SBA 504 vs a conventional bank mortgage for buying your own building: down payment, rate, fees, eligibility and what each owes at year 10, with a $2M example. SBA 504SBA loans
Glossary
All terms →More calculators
All calculators →- Refinance Break-Even Calculator Find out exactly how many months until your refinancing savings cover the closing costs. Make a data-driven decision on whether to refinance your CRE loan. Refinancing
- Cash-Out Equity Calculator Calculate how much equity you can pull from your commercial property. See your maximum cash-out amount, new loan terms, and the impact on monthly payments. Refinancing
- Yield Maintenance Calculator Estimate your prepayment penalty before refinancing or selling. Understand the true cost of exiting your commercial loan early and compare penalty structures. Refinancing