
MIXED-USE TYPES
What Type of Mixed-Use Property Are You Financing?
The commercial-to-residential ratio determines your loan type. Understanding the split is the first step in finding the right financing.
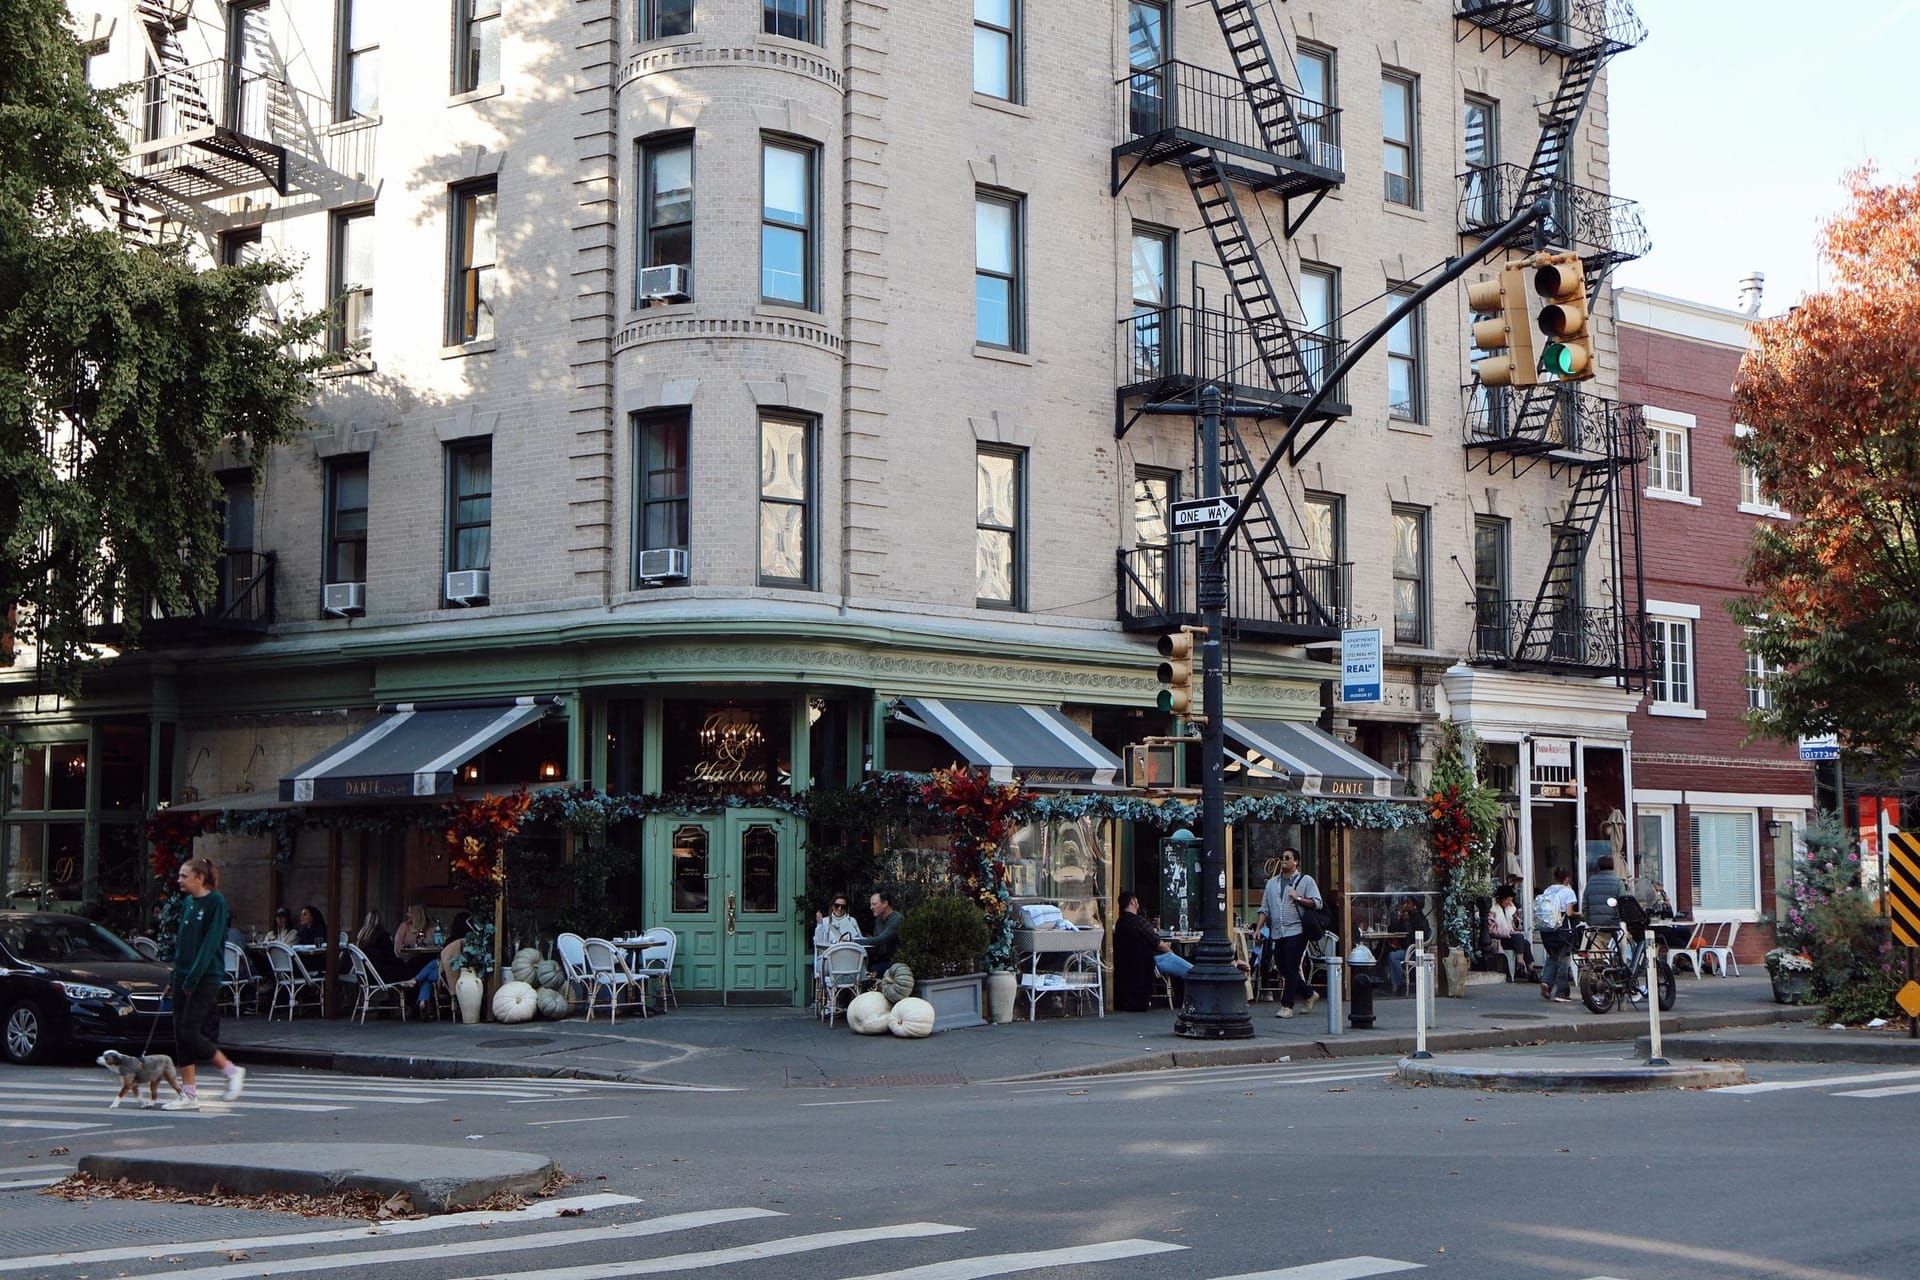
Retail + Residential
Ground-floor shops, upper-floor apartmentsThe classic Main Street format. Retail or restaurant on the ground floor with apartments or condos above. Two income streams mean one vacancy does not stop all the rent.
Office + Residential
Professional space + living unitsOffice suites on lower floors with residential units above. Common in mid-rise buildings. Lenders look at the office leases’ length and tenant quality alongside the residential rent roll.
Live-Work / Owner-Occupied
Business downstairs, home upstairsThe owner operates a business on the ground floor and lives above. SBA eligible if the business occupies at least 51% of the whole building’s rentable space (60% for new construction) — apartments count as leased space. SBA 504 starts at 10% down (15–20% for a newer business).
CRITICAL RULE
The 51% Rule for Mixed-Use Financing
The commercial vs residential split determines which loan type applies. It is one of the first things a lender checks.
51%+ Commercial
Commercial loan appliesMany lenders treat a building that is mostly commercial by square footage as commercial property, and conventional, DSCR and CMBS options apply. Each lender sets its own cutoff.
Under 51% Commercial
Residential loan may applyIf residential exceeds 51%, some lenders classify as residential. However, many portfolio lenders will still underwrite as commercial. The split determines your options.
SBA 504 / 7(a)
Owner-occupied mixed-use, from 10% downYour business must occupy at least 51% of the whole building’s rentable space (60% for new construction), and residential units count as leased space. You can lease the rest — commercial or residential — to tenants.
DSCR Loan
Investment mixed-use, no income docsInvestors buying mixed-use for cash flow. Combined commercial + residential NOI used for qualification. No personal tax returns.
Typical ranges, updated September 2026. Your terms depend on the property, the borrower and the lender.
WORKED EXAMPLE
Example: Does Your Mixed-Use Building Qualify for SBA — and What Does It Support?
Example: a $1,600,000 building with 3,000 square feet of ground-floor retail and five apartments upstairs (4,000 square feet), 7,000 square feet in all.
The SBA test. A business that would occupy the whole ground floor uses 3,000 ÷ 7,000 = 43% of the building. The apartments count as leased space, so it falls short of SBA’s 51% minimum — it would need 3,570 square feet, for example the ground floor plus 570 square feet upstairs as office or storage. If it cannot reach 51%, the purchase is financed as an investment property instead.
The investment loan. Lenders add the two income streams but apply their own vacancy to each. Assumptions for illustration only: retail rent of $60,000 a year with 10% vacancy, apartments at $1,800 a month with 5% vacancy, $45,000 of operating expenses, a 7.0% rate, 30-year amortization, a 1.25x minimum DSCR and a 75% LTV cap — computed with our max loan calculator.
| Amount | |
|---|---|
| Retail income after 10% vacancy | $54,000 |
| Residential income after 5% vacancy (5 × $1,800 × 12) | $102,600 |
| Operating expenses | −$45,000 |
| Combined net operating income | $111,600 |
| Largest loan (DSCR limit; 75% LTV would be $1,200,000) | $1,118,000 — $7,438 a month |
| Cash down | $482,000 (30%) |
If the retail tenant left, NOI would fall from $111,600 to $57,600 — a hard hit, but the apartments would still cover the operating expenses and part of the payment. That is the diversification lenders mean when they say mixed-use can be easier to finance than a single-tenant building.
Typical ranges, updated September 2026. Your terms depend on the property, the borrower and the lender.
KEY METRICS
What Lenders Evaluate for Mixed-Use
THE PROCESS
How Mixed-Use Financing Works
Determine the Split
Calculate commercial vs residential square footage. This determines whether you need a commercial or residential loan and which programs are available.
Submit to BestLoanUSA
Share property details, unit mix, rent roll for both commercial and residential, and your intended use (investment or owner-occupied).
Advisor Review
Dedicated advisor analyzes the commercial-residential split, combined income streams, and your goals to recommend the optimal loan structure.
Lender Matching
We submit to lenders experienced in mixed-use underwriting. You compare the offers that come back.
Underwriting & Appraisal
Mixed-use appraisal evaluating both components. Provide commercial leases, residential rent roll, and combined operating statements.
Close & Fund
Conventional: 30–45 days. SBA: 30–90 days. DSCR: 21–35 days.
Free tools
Run the numbers
The same metrics a lender checks — free, instant, no signup. Each result links straight into an application.
- DSCR Calculator Calculate your Debt Service Coverage Ratio instantly. See if your property qualifies for CRE financing and which loan programs are available to you.
- Cap Rate Calculator Calculate capitalization rate, estimate property value from NOI, or find the NOI needed to hit your target cap rate. The essential CRE investment metric.
- Commercial Mortgage Calculator Estimate your monthly CRE loan payment, total interest cost, and full amortization schedule. Compare loan structures before you apply.
FAQ
Frequently Asked Questions
How do mixed-use loans work?
A mixed-use loan is a commercial mortgage on a building with both commercial and residential space. The lender adds the two income streams, applies a vacancy assumption to each, and sizes the loan as the lower of a loan-to-value cap and the amount the combined net operating income repays at its minimum DSCR. In our example, $111,600 of combined NOI supports $1,118,000 on a $1,600,000 building. An owner-occupant whose business uses at least 51% of the building may use SBA 504 or 7(a) instead.
Can I get a residential mortgage on a mixed-use property?
Only for a small building that is mainly a home. Residential lenders generally finance a one- to four-unit property with a modest business space when you live there and the property stays primarily residential. Buildings with significant storefront or office space — or five or more apartments — need a commercial, DSCR or SBA loan.
How do you finance a mixed-use construction project?
With a construction loan sized on total cost, usually 65–80% LTC, funded in draws and repaid by a permanent loan once both the commercial and residential space lease up. An owner-occupant building for its own business can use SBA 504 if it will occupy at least 60% of the new building at completion. Lenders want pre-leasing on the commercial space and a realistic residential lease-up schedule.
Is mixed-use harder to finance than single-use CRE?
Not necessarily. The two income streams (commercial + residential) mean one vacancy does not stop all the rent, though lenders underwrite each part with its own assumptions. The key challenge is finding lenders comfortable underwriting both components together. Portfolio banks and some DSCR lenders regularly do.
How does the 51% rule work?
It is a lender convention, not a law: many lenders treat a building that is mostly commercial by square footage as commercial property, and one that is mostly residential may qualify for residential or portfolio loans, depending on the lender. SBA has its own rule: your business must occupy at least 51% of the whole building’s rentable space (60% for new construction), and residential units count as leased space.
Can I live in a mixed-use building I buy with an SBA loan?
SBA loans are for business use. The residential units count as leased space, not business space, in SBA’s 51% occupancy test, so an apartment you live in does not help you qualify — ask the lender how it treats an owner’s residence. However, if you operate your business on the ground floor and rent the residential units above to tenants, that's the standard SBA mixed-use structure. Separate residential financing may be needed for a live-work arrangement.
How is NOI calculated for mixed-use?
Combined. Commercial rents + residential rents - total operating expenses = combined NOI. Lenders may apply different vacancy assumptions to each component (e.g., 5% for residential, 10% for commercial). The combined NOI is then used for DSCR calculation.
What are the advantages of mixed-use investment?
Diversified income reduces risk — if a commercial tenant leaves, residential income continues and vice versa. Some cities also offer zoning or density incentives for mixed-use projects — check the local code.
What zoning do I need?
Mixed-use requires zoning that permits both commercial and residential use. Many cities have mixed-use zoning districts; names vary by city. Some properties may need a conditional use permit. Verify zoning before purchase — lenders require confirmation.
Related on BestLoanUSA
Financing options
All loans →- What Is a CRE Loan? A commercial real estate loan is financing for income-producing or business-use property — offices, retail, industrial, multifamily (5+ units) — underwritten on the property’s cash flow and value as well as the borrower, not a home mortgage. Mixed-useMultifamily
- Investment Property An investment property loan finances a building you own to rent out — multifamily, retail, office, industrial or mixed-use — and is underwritten mainly on the property’s income. Bank, DSCR, CMBS and agency lenders typically lend up to 75–80% of value at about 6.5–8.75%. DSCRLoan-to-value
- Office An office building loan finances the purchase or refinance of office property, from a single-tenant building to a multi-tenant complex. A business that occupies the space can use SBA 504 with as little as 10% down; investors use bank or DSCR loans, typically up to 75–80% of value. DSCROffice buildings
- CRE Refinancing A commercial real estate refinance replaces your existing mortgage with a new loan — to lower the rate, replace a maturing balloon, move from floating to fixed, or take cash out. To refinance, check your current loan’s maturity and prepayment penalty, get the property appraised, show that its net operating income covers the new payment at the lender’s minimum DSCR, compare term sheets and close — the new lender pays off the old loan, usually in 30–60 days. Bank, SBA 504, CMBS and DSCR lenders price refinances at about 6.25–8.75%. DSCRMixed-use
Guides & articles
All articles →- The 2026 CRE Maturity Wall: Refinancing a Loan That Comes Due $875 billion of commercial mortgages are scheduled to mature in 2026. How to size the gap when a low-rate loan refinances at today’s rates, and how to close it. MultifamilyDSCR
- Commercial Real Estate Loans for Investors vs. Residential How commercial real estate loans differ from residential mortgages — underwriting on property income, loan types, terms and the lenders involved. MultifamilyDSCR
- Multifamily Loans: How to Finance a 5+ Unit Apartment Building How financing changes at five units: multifamily loan types, how lenders underwrite an apartment building's income, and what they require. MultifamilyDSCR
Glossary
All terms →More calculators
All calculators →- NOI Calculator Calculate your property's Net Operating Income with a detailed income and expense breakdown. NOI drives your DSCR, cap rate, and property valuation. NOIDSCR
- Debt Yield Calculator Calculate Debt Yield (NOI ÷ Loan Amount) — the metric CMBS and institutional lenders prioritize over DSCR and LTV. Find your maximum loan amount based on target debt yield. DSCRNOI
- Price Per Unit Calculator Calculate per-unit pricing for multifamily properties. Compare apartment buildings on a per-door basis and estimate property value from target per-unit pricing. Multifamily