
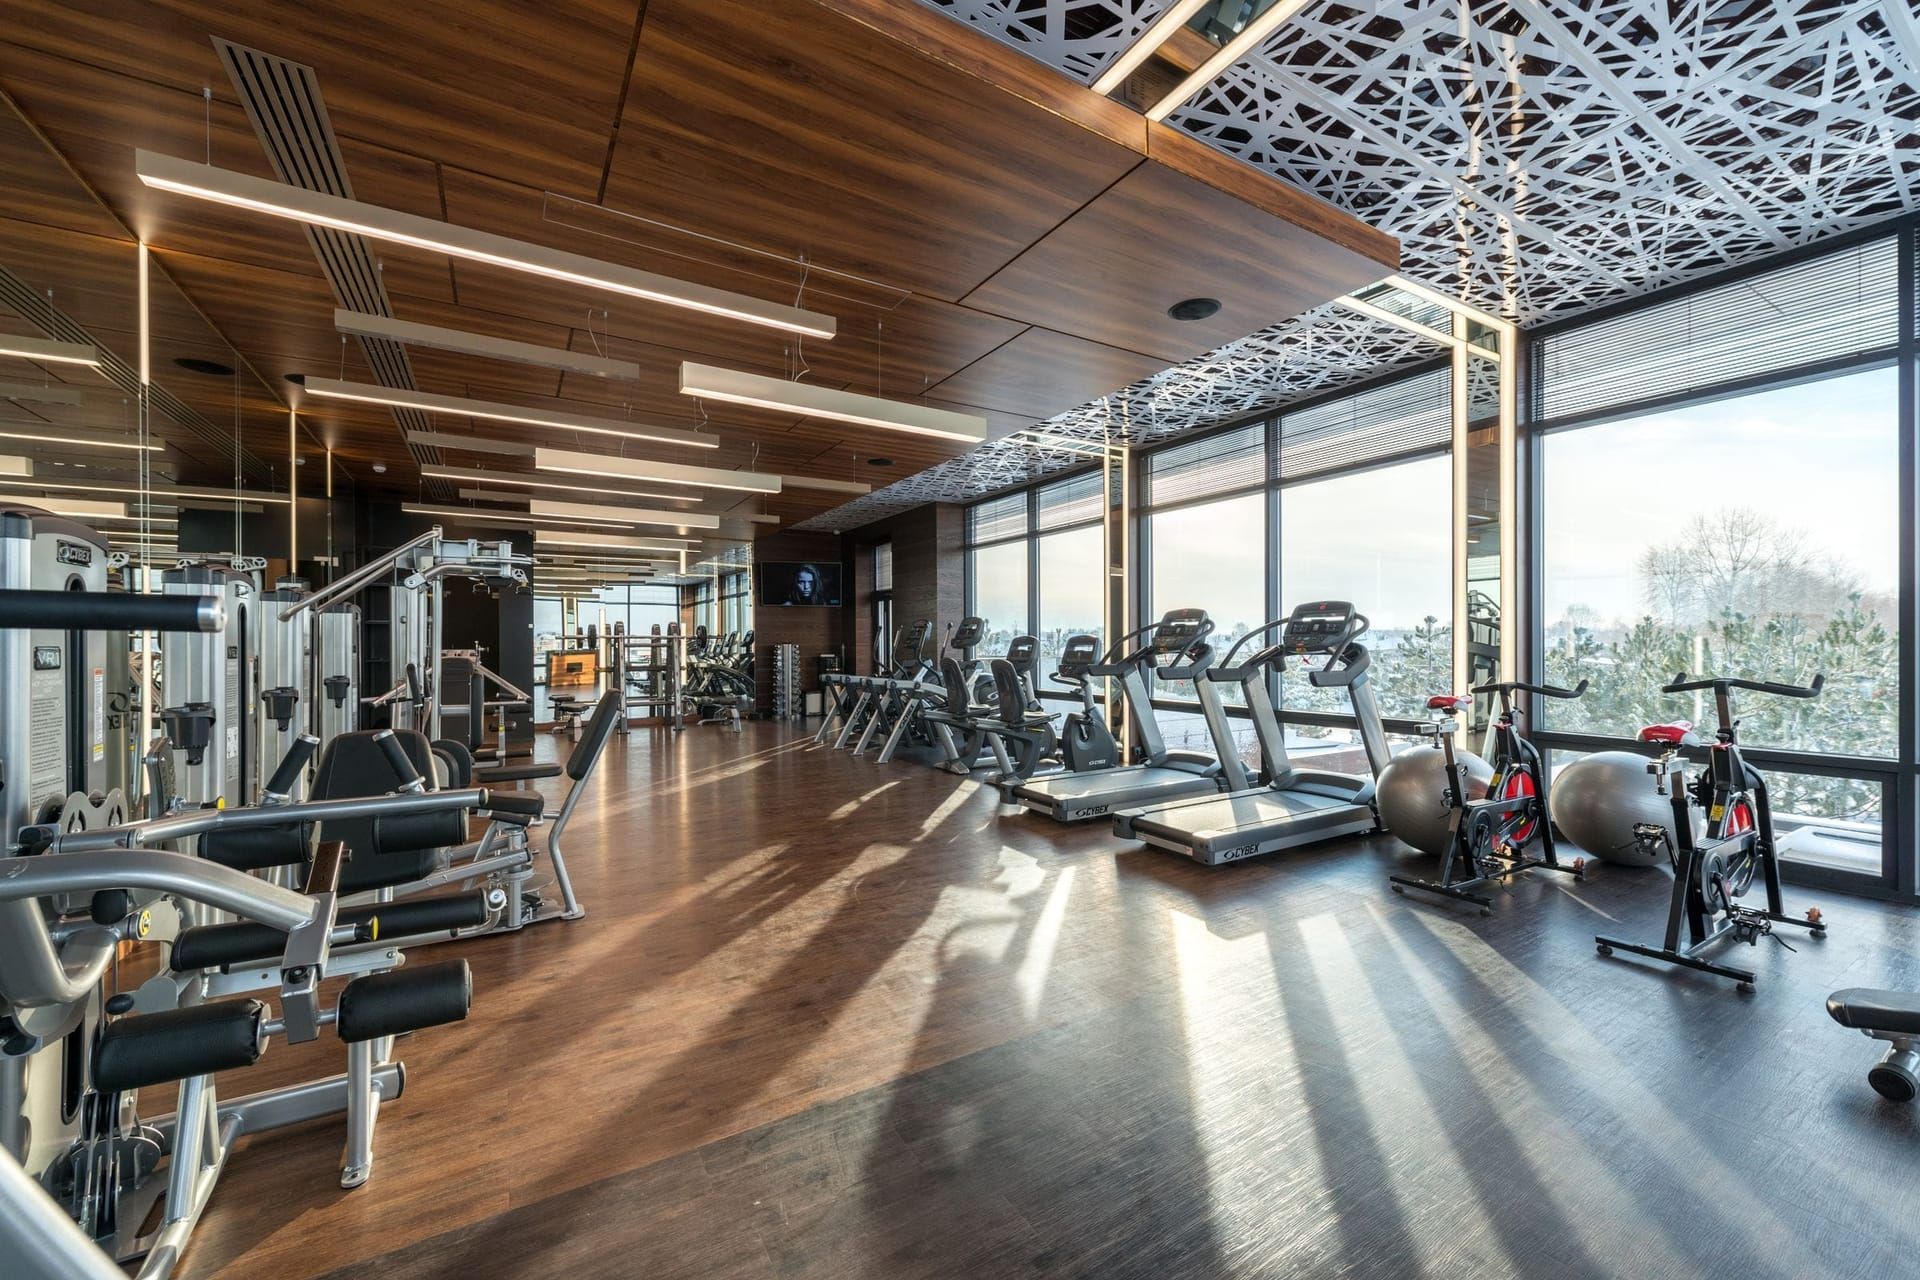
GYM TYPES
What Type of Fitness Facility Are You Financing?
Gym models differ widely. Lender appetite and financing structure vary by gym model and membership economics.
Boutique Studio
CrossFit, F45, Orangetheory, yoga, pilatesSmall footprint (1,500–5,000 sqft) with specialized programming. For an SBA loan, a franchise brand must be listed in the SBA Franchise Directory. Lower buildout cost but premium equipment.
Full-Service Health Club
Large format, multiple amenities10,000–40,000+ sqft with cardio, weights, group fitness, pool, basketball, childcare. Higher buildout and equipment cost. SBA 504 can finance the building, buildout and long-life equipment together.
Budget / HVLP Gym
Planet Fitness, Crunch, EoS modelHigh volume, low monthly price. Lower revenue per member offset by a large membership base. Lenders look at membership counts and the franchisor’s track record. Lean staffing model.
FINANCING OPTIONS
Loan Options for Fitness Properties
Gym financing is driven by membership economics and operator track record. Franchise backing can widen lender options.
SBA 504
Best for buying your gym buildingCovers real estate + buildout + major equipment (cardio machines, strength equipment, flooring). 10% down for a general-purpose building; 15% when the gym counts as special-purpose property (20% for a business under two years old).
SBA 7(a)
Franchise acquisition + buildoutCombine franchise fee, real estate or lease deposit, buildout, equipment, and working capital. The most flexible option for new gym launches.
Conventional Bank
Established operators, multi-unitBest for multi-unit franchise operators with proven performance. Lenders may price several locations together.
Equipment Financing
Cardio, strength, specialty equipmentTreadmills, ellipticals, rowers, strength machines, free weights, specialty rigs. Equipment lease or loan with the equipment as collateral. Plan for periodic equipment refresh.
Typical ranges, updated September 2026. Your terms depend on the property, the borrower and the lender.
KEY METRICS
What Lenders Evaluate for Gym Loans
WORKED EXAMPLE
Example: Financing a Gym Buildout — and Why Churn Matters
Most gyms lease their space, so the loan pays for buildout and equipment, not a building. Lenders keep that loan within the lease term, including renewal options, and size it on membership cash flow. Assumptions for illustration only: a $1,200,000 buildout and equipment package, 10% equity, an SBA 7(a) loan of $1,080,000 over 10 years at Prime 7.00% + 2.75%, computed with our SBA 7(a) calculator.
| Amount | |
|---|---|
| SBA 7(a) loan (10 years, 9.75%) | $1,080,000 — $14,123/mo |
| Annual debt service | $169,476 |
| Cash flow needed at 1.25x | about $211,845 |
| Membership revenue: 1,800 members × $45/month | $972,000 a year |
| If membership falls 15% (to 1,530) | −$145,800 a year |
A gym’s costs — rent, staff, utilities — barely move when members leave, so most lost revenue comes straight out of cash flow: a 15% drop in members here removes close to 70% of the cash flow the loan needs. That is why lenders ask for trailing membership reports, monthly churn and how many new members join each month, not just a current count.
Typical ranges, updated September 2026. Your terms depend on the property, the borrower and the lender.
THE PROCESS
How Gym Financing Works
Define Your Project
Buying a gym, building out a franchise location, or purchasing equipment? Share property details, concept, member count, and equipment needs.
Submit to BestLoanUSA
Single application with business financials and franchise agreement (if applicable). No hard credit pull.
Advisor Review
Dedicated advisor evaluates your fitness model, membership economics, franchise standing, and property requirements to recommend the best financing structure.
Lender Matching
We submit to fitness-experienced lenders. Franchise operators may reach lenders their franchisor already works with. You compare the offers lenders return.
Underwriting & Appraisal
Provide trailing 12-month P&L, membership reports, franchise agreement, equipment quotes, and buildout estimates.
Close & Build/Operate
SBA 7(a): 30–60 days. SBA 504: 60–90 days. Conventional: 30–45 days. Equipment: usually faster than real estate loans. Buildout time depends on scope; full-service clubs take longer than boutique studios.
Free tools
Run the numbers
The same metrics a lender checks — free, instant, no signup. Each result links straight into an application.
- SBA 504 Loan Calculator Estimate your SBA 504 loan structure — see the three-part split (borrower, CDC, bank), monthly payments for each portion, and total project financing.
- Commercial Mortgage Calculator Estimate your monthly CRE loan payment, total interest cost, and full amortization schedule. Compare loan structures before you apply.
FAQ
Frequently Asked Questions
Should I buy or lease my gym space?
If you plan to operate 5+ years, buying locks in occupancy cost and builds equity. SBA 504 makes this accessible with 10–15% down (15% when the gym building counts as special-purpose property). Gym buildouts (flooring, showers, HVAC) are expensive to replicate, so owning protects your investment. Many successful gym owners lease initially, prove the concept, then buy.
How much can I borrow to open or expand a gym?
Lenders size the loan on membership cash flow and keep a leasehold buildout loan within your lease term. In our example, a $1,080,000 SBA 7(a) loan over 10 years costs $14,123 a month, so the gym needs about $211,845 of yearly cash flow to cover it 1.25 times — from a base of 1,800 members paying $45 a month.
Does franchise backing help with gym financing?
Often. For an SBA loan the brand must be listed in the SBA Franchise Directory. Lenders also weigh the franchisor’s unit economics, operational systems and marketing support, which can reduce lender risk compared with an independent gym.
How much does gym equipment cost?
Boutique studio: $50K–$150K (specialty rigs, bikes, rowers). Full-service gym: $300K–$1.5M (full cardio floor, strength circuit, free weights, functional training area). Equipment financing with 3–7 year terms is available. Most operators plan for equipment refresh every 3–5 years.
Can I open a gym with no experience?
Many franchise models are built for operators without gym industry experience — the franchise provides the playbook. Many SBA lenders will consider franchise-backed first-time operators. Independent gyms require demonstrated fitness industry experience for most lenders.
How has COVID affected gym lending?
Lenders finance gyms again, but many ask for trailing 24-month financials and membership trends to show revenue has held up. Franchise brands with published unit data are generally easier to underwrite than new independent concepts.
What buildout costs should I expect?
It depends on the format. Boutique studios mainly need rubber flooring, mirrors and HVAC. Full-service gyms add locker rooms, showers, sometimes a pool, group fitness rooms and upgraded HVAC and electrical. Budget gyms use open floor plans with few wet areas. Get contractor bids before you size the loan.
Related on BestLoanUSA
Financing options
All loans →- Dental Office A dental office loan finances the space a practice operates from — buying the building or condo, financing a buildout, or acquiring a practice with its real estate. Dentists who occupy the space can use SBA 504 or 7(a) with as little as 10% down. Tenant improvementsSBA 7(a)
- Tenant Improvement Tenant improvement (TI) financing pays for the buildout of a commercial space — walls, electrical, HVAC, fixtures — whether you own the building or lease it. Owners can roll TI into an SBA 504 or conventional loan; tenants often combine SBA 7(a) with the landlord’s TI allowance. Tenant improvementsSBA 7(a)
- Medical Office A medical office loan finances a building used for healthcare — a physician practice, outpatient clinic or surgery center. Practitioners who occupy it can use SBA 504 or 7(a) with up to 90% financing; investors buying a leased medical building use bank or DSCR loans. Tenant improvementsSBA 504
- Restaurant A restaurant property loan finances the building a restaurant operates from — buying it, building out the space or refinancing. Owner-operators who occupy the property can use SBA 504 or 7(a) with as little as 10% down; investors buying a leased restaurant use bank or DSCR loans. Tenant improvementsSBA 504
Guides & articles
All articles →- Restaurant Building Loans: Buying vs. Leasing Your Location Buying vs. leasing a restaurant building: how owners finance the property with SBA and bank loans, and when owning your location pays off. Tenant improvementsSBA 7(a)
- SBA 7(a) vs. SBA 504: Which SBA Loan Do You Actually Need? Both are SBA loans — but they work completely differently and are right for different situations. Here's the side-by-side that tells you which one fits your need. SBA 7(a)SBA 504
- Business Loans for Contractors: Construction Financing Options Financing options for construction companies — lines of credit, equipment loans, factoring and SBA — and how each handles slow pay and upfront job costs. Equipment financingSBA 504
Glossary
All terms →More calculators
All calculators →- TI Allowance Calculator Calculate tenant improvement budgets and total build-out costs. Understand how TI allowances affect your lease economics and landlord investment. Tenant improvements
- SBA 7(a) Payment Calculator Estimate monthly payments on an SBA 7(a) loan with Prime + spread variable rate. See how rate changes affect your payment and plan for different scenarios. SBA 7(a)SBA loans