Typical ranges, updated September 2026. Your terms depend on your revenue, credit, time in business and the lender.
Worked example
What a Salon Buildout Needs from Each Chair
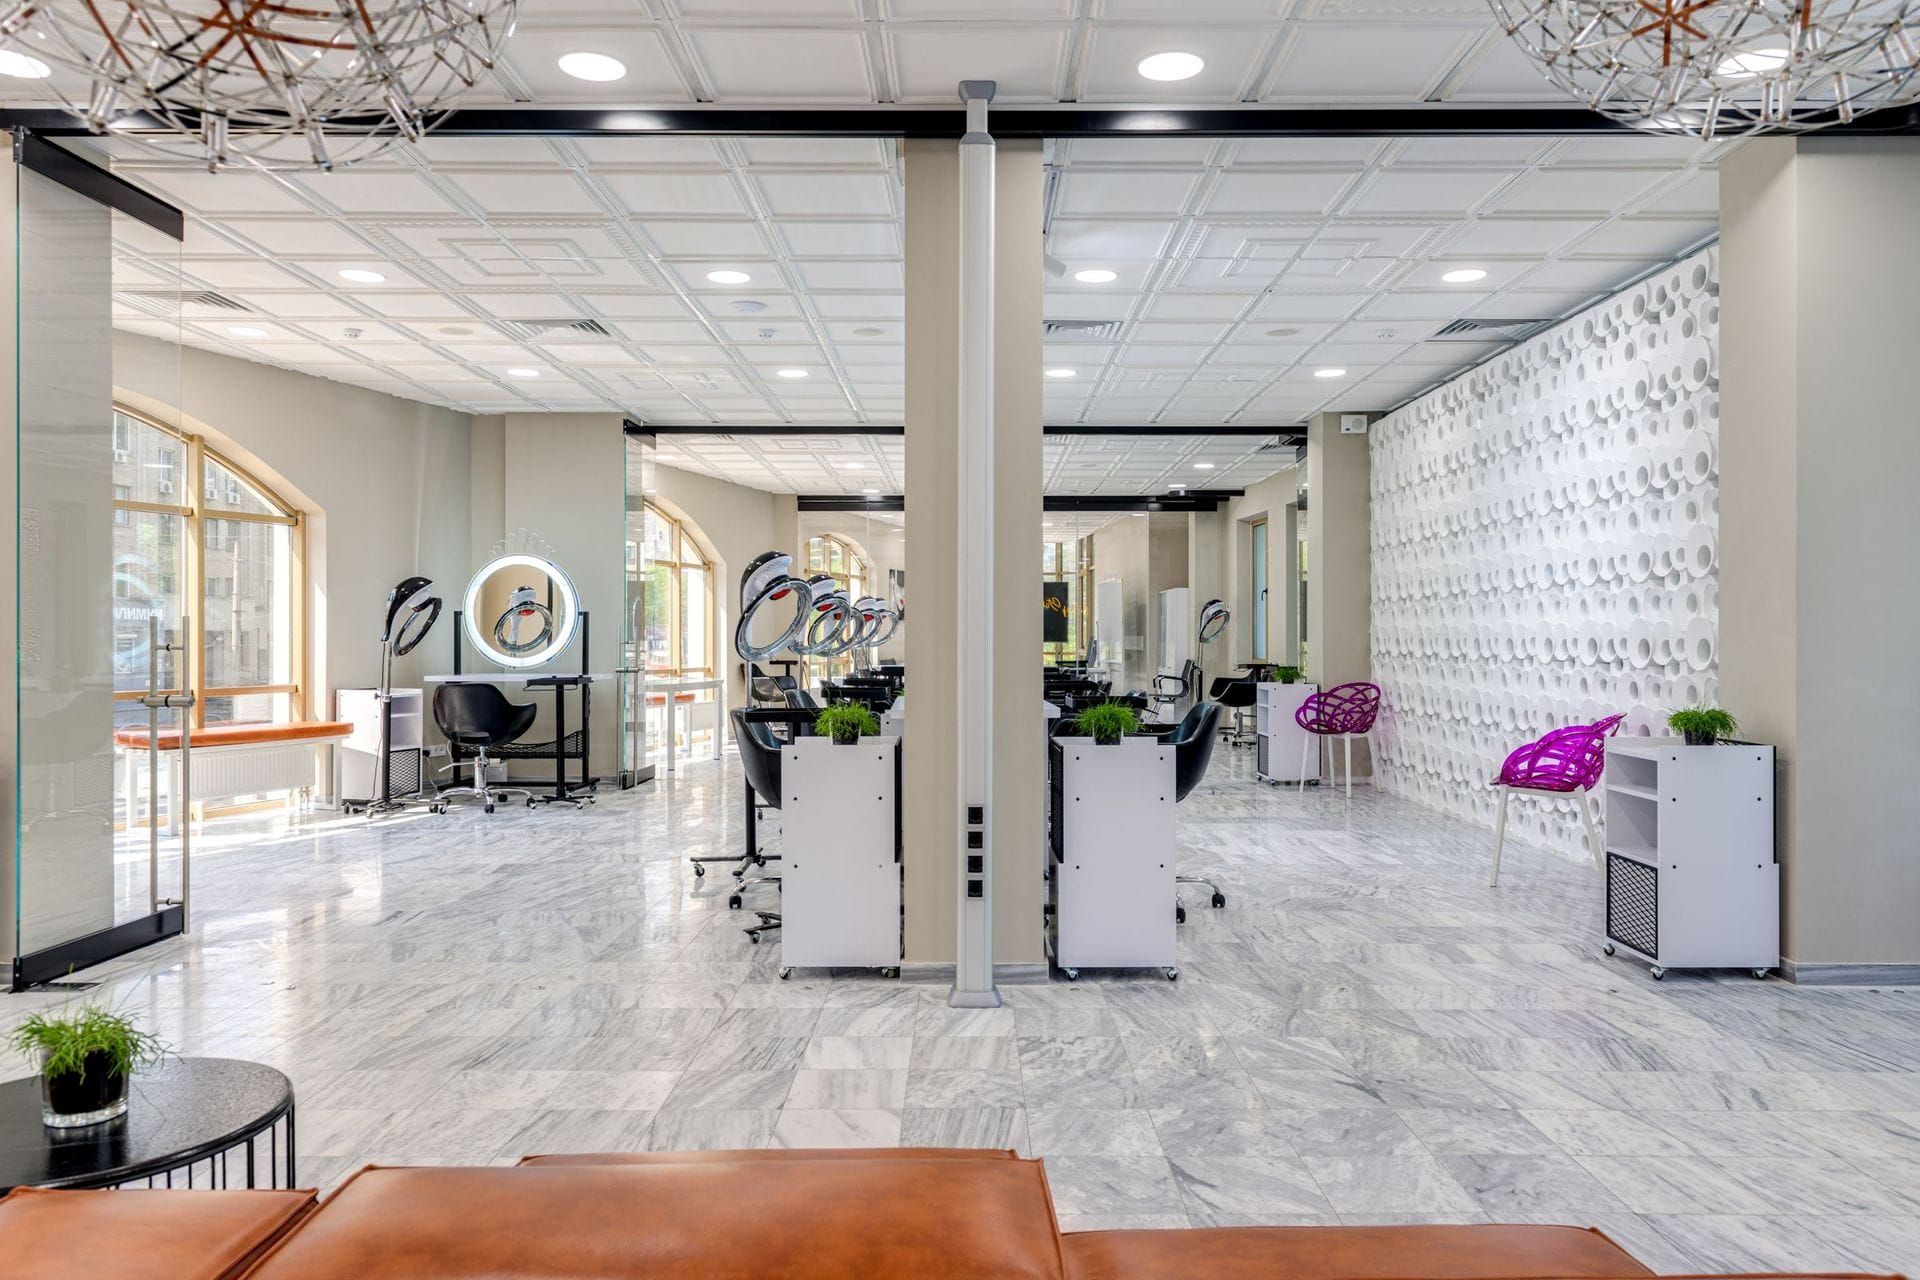
Example: a salon owner opens a second, 10-chair location in leased space: $250,000 of buildout and $80,000 of equipment. Assumptions for illustration only: 10% equity, a 10-year SBA 7(a) loan at Prime 7.00% + 2.75% (lenders keep a leasehold buildout loan within the lease term, including renewal options), computed with our SBA 7(a) calculator.
Amount
Buildout + equipment
$330,000
Equity (10%)
$33,000
SBA 7(a) loan, 10 years, 9.75%
$297,000 — $3,884/mo
Cash flow needed at 1.25x coverage
about $58,300 a year
Per chair, per month
about $486
Framing the loan per chair shows whether the plan works: if each chair — whether staffed by employees or rented to stylists — produces well over $486 a month of cash flow after its own costs, the payment is covered. Booth-rent income is steady but capped; commission chairs can earn more but depend on bookings. Lenders will ask which model you run and for the first location’s results.
FAQ
Salon & Spa Loan FAQs
Common questions about salon and spa financing
What documents do I need to apply for a salon loan?
Typically you will need 3–6 months of business bank statements, recent tax returns, a valid business license, and a government-issued ID. Equipment financing may only require bank statements and an equipment invoice. SBA loans need additional documentation including a business plan and 2 years of financials.
How much can I borrow to open a new salon location?
Lenders size it on the cash flow the location can produce and keep a buildout loan within your lease term. In our example, a $330,000 buildout and equipment package with 10% down is a $297,000, 10-year SBA 7(a) loan costing $3,884 a month — about $486 per chair per month of cash flow at 1.25x coverage for a 10-chair salon.
How long does it take to get approved?
Equipment financing can be approved in 1–3 business days. Business lines of credit and term loans take 3–14 days. SBA loans take 30–90 days.
What credit score do I need to qualify?
SBA loans typically need 680+, term loans 620+, lines of credit 650+, and equipment financing 600+. If your score is below 620, focus on equipment financing while building your credit profile over 6–12 months.
Can I get a loan for a new salon with no business history?
Yes, but options are more limited. Startup loans, SBA microloans, and equipment financing are the most accessible. Some alternative lenders approve businesses under 1 year if you show $10K+/month in revenue. A strong personal credit score and detailed business plan significantly improve your chances.
What can I use the loan funds for?
Most business loans can be used for equipment, renovations, staffing, inventory, marketing, and working capital. Equipment financing is restricted to specific equipment purchases. SBA loans are the most flexible and can fund nearly any business purpose including real estate.
Are there any prepayment penalties?
This varies by lender and loan type. Many modern online lenders offer loans without prepayment penalties. Traditional bank loans and SBA loans may have prepayment penalties in the first 1–3 years.